
Sovereign Default
A sovereign default is a government's failure to pay its debts, with no court to enforce repayment and consequences that are mostly political.
A sovereign default happens when a government fails to pay back the money it owes. If a company goes bankrupt, a court can seize its property and distribute it to the people it owes. No court has that power over a country. Nobody can repossess a nation. That fact is the reason government debt works differently from every other kind: it determines who lends, at what price, and why a default always ends in negotiation rather than in a legal ruling.
Governments have been defaulting for as long as they have been borrowing. The Habsburg kings of Spain stopped paying their creditors at least six times between the 1550s and the 1660s, even as silver from the Americas poured into their treasury. During the Great Depression, defaults swept across Latin America and large parts of Europe. Since 2020 alone, Zambia, Sri Lanka, and Ghana have all stopped servicing their debts.
Why governments pay their debts
If no court can compel payment, the question is what keeps countries honest. Four things do most of the work: a government's reputation with lenders, the knowledge that it will need to borrow again, the trade credit its businesses rely on for imports, and the risk that foreign courts will freeze the country's overseas assets.
For most of modern history, a fifth factor mattered too: military force. In 1902, Britain, Germany, and Italy blockaded Venezuela's coast after its president refused to honor the country's obligations. Egypt stopped paying its creditors in 1876. Within six years, Britain occupied the country outright. The Ottoman Empire defaulted a year earlier, in 1875, and European lenders responded by creating the Public Debt Administration, which took over the collection of several Ottoman taxes. At its height, that organization employed roughly 9,000 officials, outnumbering the empire's own treasury staff. Again and again, default opened the door to foreign control.
Why defaults come in clusters
Sovereign defaults rarely happen one at a time. Their triggers are usually global: a crash in commodity prices, a spike in borrowing costs set by a major creditor country, or a war. When conditions shift, many governments hit the wall at once.
The most important modern example began in August 1982. Mexico's finance minister, Jesús Silva-Herzog, told the IMF that his country could no longer meet payments on roughly $80 billion in debt. That admission triggered a cascade across Latin America. One country after another found that the same pattern, easy borrowing in the 1970s followed by sharply higher American interest rates, had made its debts unmanageable. A decade of stagnation followed. The way out came in 1989, when US Treasury Secretary Nicholas Brady proposed converting bank loans into tradable bonds at a discount. The Brady Plan gave lenders something they could sell and gave borrowers room to breathe, and it became the model for many restructurings since.
Argentina's default and the holdout problem
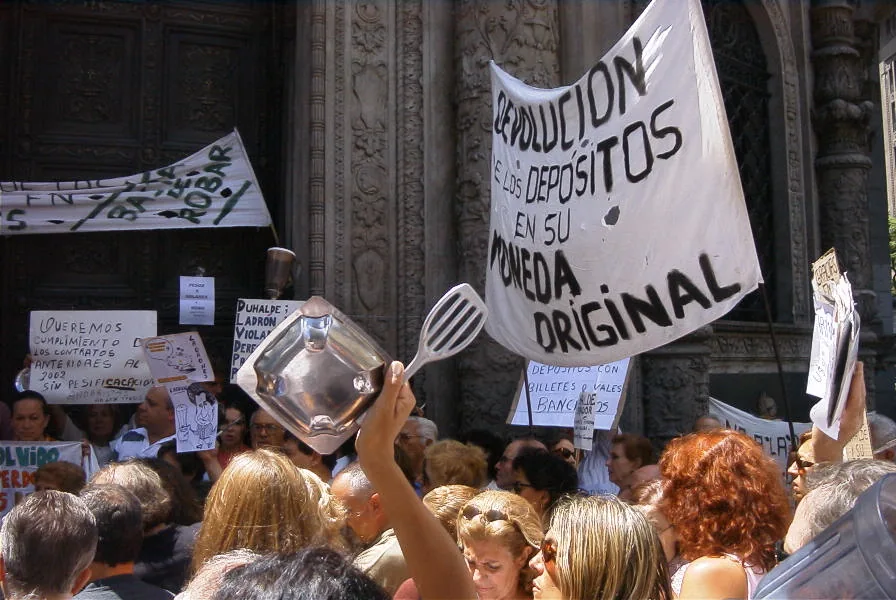
Argentina's 2001 default was, at the time, the largest on record. The government stopped paying on about $82 billion in bonds in the middle of a bank run so severe that authorities capped cash withdrawals, a step Argentines nicknamed the "corralito," the little fence.
Argentina offered its creditors new bonds in 2005 and 2010, worth roughly a third of the originals. The vast majority accepted. A handful did not. These holdout creditors, mostly hedge funds, had purchased the old bonds at steep discounts after the default and then sued Argentina in New York. Federal judge Thomas Griesa interpreted the bonds' equal-treatment clause in a way no one had expected: Argentina could not send payments to the creditors who had accepted the deal unless it also paid the holdouts every cent they were owed. The order froze those payments. In July 2014 Argentina fell into a second, technical default, not for lack of money but because the court prevented it from transferring funds to those creditors.
That episode rewrote the rules for sovereign bonds. New issues now routinely include collective action clauses, which allow a supermajority of creditors to force holdouts into a restructuring agreement.
What default does to a country
The short-term hit is economic. A country's economic output typically falls steeply in the year it defaults. Banks that hold the government's bonds absorb losses, and a debt crisis can quickly become a banking crisis. Lending within the country seizes up.
Yet most defaulting countries manage to sell new bonds within a few years. Yield-hungry investors tend to have short memories. Argentina itself placed a fresh bond offering in 2016, just weeks after resolving its fight with the holdout creditors.
The deeper cost is political, not financial. Default topples governments, discredits the policies that were in place when payments stopped, and drives the country toward whichever lender is willing to step in next. In 2012, Greece restructured roughly 200 billion euros in bonds, the largest reduction any creditor group has ever absorbed. The restructuring took place inside the eurozone, a currency union built on the assumption that no member would ever default. Years of austerity followed, reshaping Greek politics for a generation.
How restructuring works today
A modern restructuring rests on three elements. Bondholders agree to a "haircut," a package of reduced face value, lower interest, or a longer repayment schedule. Collective action clauses, now written into most new sovereign bonds, stop a small minority of creditors from blocking the deal. The IMF provides bridge financing to keep the process orderly, on terms the borrowing government almost always finds painful.
The biggest obstacle today is China. Belt and Road lending made China the single largest government creditor to dozens of developing countries. China does not belong to the Paris Club, the longstanding forum where creditor governments coordinate on debt relief. Beijing favors extending repayment schedules over accepting losses, and it handles each case on its own rather than through a shared framework. That stance is the main reason the G20's Common Framework, launched in 2020 to accelerate restructurings for the poorest countries, has produced little. Zambia applied for relief in early 2021 and waited more than two years before its bilateral creditors reached a deal.
Government debt is always more than a financial instrument. The question of who a country owes is a question about who has leverage over it, and sovereign default is the moment that question gets answered.